Mortgage Broker in Courtenay, BC

I Help Vancouver Island Homeowners Pay Off Their Mortgage Faster and Build Wealth at the Same Time.


Most people think a mortgage is just a loan you pay off for 25 years. I help my clients think about it differently. With the right strategy, your mortgage can be a tool for building long-term wealth, reducing your tax bill, and retiring sooner than you think.


I'm Dean Garrett, a mortgage broker based in Courtenay, BC, serving homeowners across Vancouver Island and all of BC. With 72 five-star Google reviews and a Smith Manoeuvre Certified Professional designation, I bring a level of strategic expertise to mortgage planning that most brokers simply don't offer.

72 Five-Star Google Reviews ★ ★ ★ ★ ★
Smith Manoeuvre Certified Professional
Serving All of Vancouver Island and across BC

Follow My Three Step Plan To Get The Ultimate Mortgage!

Tell Me Where You Are

Every mortgage situation is different. Start by booking a free call. I'll ask the right questions, listen carefully, and give you a clear picture of your options. No pressure, no forms to fill out before you're ready.

See the Full Picture

I'll map out your mortgage options across multiple lenders and show you not just how to get a mortgage, but how to structure it so it works for you over the long term. That includes strategies most homeowners never hear about from their bank.

Execute With Confidence

I handle everything. The paperwork, the lender negotiations, the follow-up. You'll know exactly where you stand at every stage, and I'll be available to answer questions for as long as you have a mortgage.
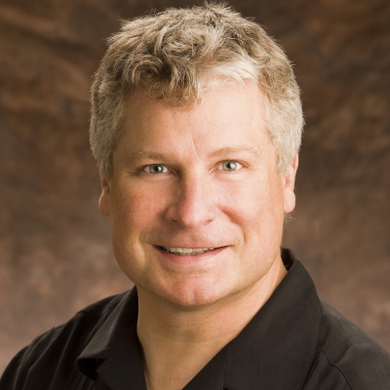
As a seasoned Mortgage Pro,

I will save you Money!

I became a mortgage broker because I believe homeowners deserve better than what the banks offer. Most Canadians are handed a mortgage, told to make payments for 25 years, and sent on their way. I think there's a smarter path.


I'm a Smith Manoeuvre Certified Professional, one of a small number of brokers in Canada who are accredited to help clients convert their non-deductible mortgage interest into tax-deductible investment debt. In plain terms: I help people use their mortgage to build wealth, not just pay down debt.


I've helped clients across Courtenay, Comox Valley, Campbell River, and all of Vancouver Island structure mortgages that work harder for them. If you're in your 30s or 40s, a homeowner or planning to become one, and you want a mortgage advisor who thinks about the long game, let's talk.

Nice things people have said about working with me.

LEAVE A REVIEW ON FACEBOOK

There are plenty of mortgage brokers on Vancouver Island. Here is what I do differently:
Strategic thinking:

I don't just get you a mortgage. I help you structure it as part of a longer financial plan.

Smith Manoeuvre expertise:

Very few brokers in BC are certified to implement this strategy. I am one of them.

Lender access:

Self-employed? New to Canada? Investment property? Complex files are my specialty, not an exception.

Transparent advice:

I'll tell you if a strategy doesn't make sense for your situation. My goal is your long-term financial health, not just a closed file.

Local knowledge:

I know Vancouver Island. I understand the communities, the market, and the unique financial situations of people who live here.

Free to you:

My services are free in most cases. The lender pays my fee when your mortgage funds.

Your Home Mortgage Interest is

NON-TAX DEDUCTIBLE

Convert your Home Mortgage into a

TAX-DEDUCTIBLE LOAN

AND pay off your mortgage in record time.

All without straining your current finances.

You don’t have to increase your required payment to ACHIEVE INCREDIBLE RESULTS!

LEARN MORE

A Smarter Way to Use Your Mortgage

Here is something your bank will never tell you. Your mortgage can be more than a debt you pay off for 25 years. With a properly structured readvanceable mortgage and a disciplined strategy, you can convert your mortgage interest into a tax deduction, build an investment portfolio simultaneously, and potentially pay off your mortgage 7 to 10 years sooner, all without increasing your monthly payments.


This is the Smith Manoeuvre, and
I am one of a small number of certified professionals in BC qualified to help you implement it correctly. It is not the right strategy for everyone. But if you are a Vancouver Island homeowner in your 30s or 40s with a stable income and a plan to stay in your home long-term, it is worth understanding.


I offer every client
a personalized analysis of whether this strategy makes sense for their situation. There is no cost and no obligation.
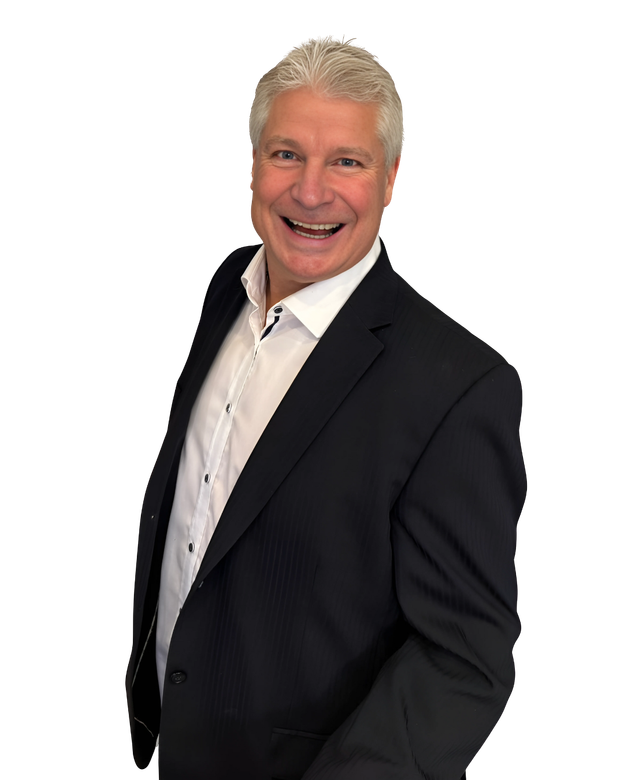
A man in a suit and white shirt is smiling for the camera.

Your path to financial freedom starts today.

As a trusted Canadian Mortgage Broker and Smith Manoeuvre Certified Professional (SMCP), I help homeowners turn mortgage debt into long-term wealth.


I specialize in Smith Manoeuvre strategies, including cash damming and debt swaps, with tax-efficient mortgage planning.
A logo for the smith manoeuvre with a graph on it.
LEARN MORE

BUY THE BOOK

Why Read The Smith Manoeuvre?

If you have a mortgage in Canada, this book can show you how to turn it into a powerful wealth-building tool. Learn how to make your interest tax-deductible, pay off your mortgage faster, and invest for your future—without spending more or increasing your debt. It's a simple strategy with life-changing potential.
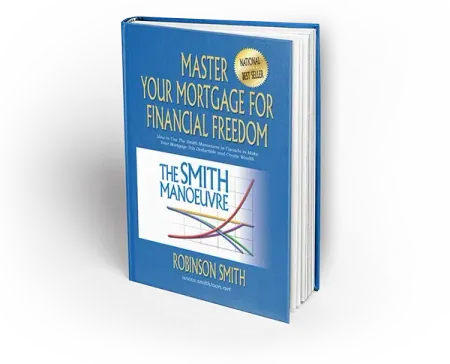
Learn more about it
A book titled master your mortgage for financial freedom

Smith Manoeuvre FAQs

  • What is the Smith Manoeuvre and is it right for me?

    The Smith Manoeuvre is a Canadian financial strategy that converts your non-deductible mortgage interest into tax-deductible investment debt. Over time, it can help you pay off your mortgage 7 to 10 years faster while building an investment portfolio, without increasing your monthly payments. It works best for homeowners with a stable income who plan to stay in their home long-term. I offer a free personalized analysis to help you determine if it makes sense for your situation.

  • Is the Smith Manoeuvre legal in Canada?

    Yes, when it’s structured correctly. The Canada Revenue Agency allows interest to be deducted when borrowed funds are used for the purpose of earning investment income. Accurate tracking, documentation, and correct setup are critical. As an SMCP®, I coordinate with your tax professional to ensure the strategy is applied appropriately.

  • Do I need a readvanceable mortgage to use the Smith Manoeuvre?

    Yes. A readvanceable mortgage combines a traditional mortgage with a HELOC. As you make payments, your available credit increases, allowing you to reinvest systematically. Without a readvanceable mortgage, the strategy cannot function as designed.

  • Who is the Smith Manoeuvre best suited for?

    It works best for disciplined homeowners who:


    • have a stable income
    • plan to own their home long-term
    • are comfortable with investing
    • pay income tax annually
    • want to build wealth more efficiently

    If cash flow is tight, risk tolerance is low, or timelines are short, we may explore alternatives or adjust the approach.


  • Is the Smith Manoeuvre risky?

    Like any investment strategy, there is risk. Investment values fluctuate, and interest rates can change. My role is to assess your cash flow, stress-test scenarios, and make sure the structure is conservative, transparent, and aligned with your tolerance and long-term plan.

  • How long before I see benefits?

    Many homeowners notice tax deduction benefits within the first couple of years. The real power compounds over 10 to 20+ years as investments grow and non-deductible mortgage interest shrinks. It’s a long-term strategy, not a quick-win tactic. The results are typically life-changing.

  • What types of investments are used?

    Generally, investments must have the potential to generate income (interest, dividends, rent, etc.). Common choices include professionally managed or self-managed portfolios, dividend-paying funds, or other market-based investments, guided by your investment advisor. Speculative investments typically don’t qualify.


  • Can I still make extra payments on my mortgage?

    Yes! And those extra payments accelerate the strategy. Each payment frees up more HELOC room, which can then be reinvested. Done correctly, your tax deductions increase while your non-deductible balance declines faster.

  • What if I move or sell my home?

    The strategy can continue if your next mortgage is appropriately structured. If you sell, we ensure everything is unwound correctly, interest remains traceable, and tax documentation is clean. Planning prevents missteps.

  • Is Cash Damming, or Rental Cash Damming, part of the Smith Manoeuvre?

    Yes! Five “Accelerators” can be applied to the Smith Manoeuvre. An accelerator will convert your non-tax-deductible mortgage debt to tax-deductible debt faster than simply using the “Plain Jane” strategy. As an SMCP®, I examine your current cash flow to determine which accelerators are available to you and demonstrate how significant the gains will be when applied.

  • Why work with an SMCP®?

    An SMCP® understands:


    • correct structure and lending options
    • CRA rules and interest traceability
    • investment and tax coordination
    • ongoing monitoring and documentation

    Most mortgages are not automatically set up to support the Smith Manoeuvre. My role is to help ensure yours is.


    This content is for educational purposes only. Always consult your tax professional and licensed investment advisor before implementing the Smith Manoeuvre.

Still have a question?

CONTACT ME

Get started by BOOKING A CALL WITH ME.

BOOK A CALL

I'll let you know exactly where you stand so you can proceed with confidence.

Everything you need, all in one place

As a trusted mortgage provider, let me help you with these services.

Click through any of the services to learn more
A living room with two chairs and a fireplace
Purchase
A living room with a couch and a coffee table
Refinance
A room with a plant on a table and a hat on a bench
Renewal
A man and a woman are sitting on the floor in front of cardboard boxes.
First Time Home Buyers
An apple laptop sits on a desk in front of a window
Self Employed
A kitchen with white cabinets and black stools
Next Home
A living room with a couch and a flat screen tv
Investment
A man and a woman wearing aprons are standing in a kitchen
Older Canadians
A woman and two children are sitting on a blue couch.
Divorce Mortgage

Mortgage articles to keep you informed.
By Dean Garrett • November 4, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
By Dean Garrett • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Dean Garrett • October 21, 2026
Why the Source of Your Down Payment Matters More Than You Think When buying a home, most people focus on how much they need for a down payment. What often gets overlooked is that where the down payment comes from matters just as much to the lender . The source of your down payment affects approval, risk assessment, and how your mortgage is structured. Here’s why lenders care—and what you need to know. 1. Anti–Money Laundering Requirements Lenders aren’t just being cautious—they’re legally required to verify the source of your down payment. To comply with anti–money laundering regulations, lenders must document where every dollar of the down payment came from on every purchase. Acceptable Down Payment Sources Down payments can come from: Your own savings or investments Borrowed funds through an insured program (such as FlexDown) A gift from an immediate family member How You Prove the Source Personal savings: You’ll need bank statements showing the funds have been in your account for at least 90 days , or proof they were accumulated through payroll deposits or other acceptable sources. Borrowed funds: Any borrowed portion must be included in your debt service ratios , since you’re responsible for repayment. Gifted funds: A signed gift letter is required confirming the money is a true gift with no repayment obligation , along with proof the funds were deposited into your account. 2. Financial Suitability and Risk The source of your down payment also tells the lender a lot about your financial habits. Down payments coming from your own savings demonstrate: Positive cash flow The ability to save consistently Strong financial management This reassures lenders that you’re more likely to keep up with mortgage payments. If the down payment is borrowed or gifted, lenders may look more closely at the rest of your application to ensure the mortgage remains affordable. Why a Larger Down Payment Helps From a lender’s perspective, more equity equals lower risk. The more money you have invested in the property, the less likely you are to walk away from the mortgage. This reduces the lender’s exposure and can sometimes result in better terms. 3. Down Payment and Loan-to-Value (LTV) Your down payment directly establishes your loan-to-value ratio (LTV)—the percentage of the property’s value being financed. In Canada: Lenders can finance up to 95% of a property’s value The buyer must contribute at least 5% as a down payment Example: On a $400,000 purchase: Maximum mortgage = $380,000 Minimum down payment = $20,000 How the Source Affects LTV Property value must be genuine and independently supported. Lenders rely on appraisals and comparable sales—not artificial price inflation. If: The seller provides money back The buyer doesn’t bring the full down payment independently Funds move “behind the scenes” …the lender considers this a change to the LTV and may decline the mortgage. All financial details of the purchase must be fully disclosed. Non-disclosure is mortgage fraud , and lenders will not proceed if the numbers don’t align. Final Thoughts Lenders ask for detailed documentation about your down payment source for good reason—it affects legality, risk, and the structure of your mortgage. Understanding these rules upfront helps avoid delays, declined applications, and last-minute surprises. If you’d like to review your down payment options or talk through mortgage financing, feel free to connect anytime. I’d be happy to walk you through the process and help you plan with confidence.
By Dean Garrett • November 4, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
By Dean Garrett • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Dean Garrett • October 21, 2026
Why the Source of Your Down Payment Matters More Than You Think When buying a home, most people focus on how much they need for a down payment. What often gets overlooked is that where the down payment comes from matters just as much to the lender . The source of your down payment affects approval, risk assessment, and how your mortgage is structured. Here’s why lenders care—and what you need to know. 1. Anti–Money Laundering Requirements Lenders aren’t just being cautious—they’re legally required to verify the source of your down payment. To comply with anti–money laundering regulations, lenders must document where every dollar of the down payment came from on every purchase. Acceptable Down Payment Sources Down payments can come from: Your own savings or investments Borrowed funds through an insured program (such as FlexDown) A gift from an immediate family member How You Prove the Source Personal savings: You’ll need bank statements showing the funds have been in your account for at least 90 days , or proof they were accumulated through payroll deposits or other acceptable sources. Borrowed funds: Any borrowed portion must be included in your debt service ratios , since you’re responsible for repayment. Gifted funds: A signed gift letter is required confirming the money is a true gift with no repayment obligation , along with proof the funds were deposited into your account. 2. Financial Suitability and Risk The source of your down payment also tells the lender a lot about your financial habits. Down payments coming from your own savings demonstrate: Positive cash flow The ability to save consistently Strong financial management This reassures lenders that you’re more likely to keep up with mortgage payments. If the down payment is borrowed or gifted, lenders may look more closely at the rest of your application to ensure the mortgage remains affordable. Why a Larger Down Payment Helps From a lender’s perspective, more equity equals lower risk. The more money you have invested in the property, the less likely you are to walk away from the mortgage. This reduces the lender’s exposure and can sometimes result in better terms. 3. Down Payment and Loan-to-Value (LTV) Your down payment directly establishes your loan-to-value ratio (LTV)—the percentage of the property’s value being financed. In Canada: Lenders can finance up to 95% of a property’s value The buyer must contribute at least 5% as a down payment Example: On a $400,000 purchase: Maximum mortgage = $380,000 Minimum down payment = $20,000 How the Source Affects LTV Property value must be genuine and independently supported. Lenders rely on appraisals and comparable sales—not artificial price inflation. If: The seller provides money back The buyer doesn’t bring the full down payment independently Funds move “behind the scenes” …the lender considers this a change to the LTV and may decline the mortgage. All financial details of the purchase must be fully disclosed. Non-disclosure is mortgage fraud , and lenders will not proceed if the numbers don’t align. Final Thoughts Lenders ask for detailed documentation about your down payment source for good reason—it affects legality, risk, and the structure of your mortgage. Understanding these rules upfront helps avoid delays, declined applications, and last-minute surprises. If you’d like to review your down payment options or talk through mortgage financing, feel free to connect anytime. I’d be happy to walk you through the process and help you plan with confidence.
Show More

Go ahead and schedule a meeting with me!

Mortgage FAQs for Canadian Homeowners

  • What makes you different from other mortgage brokers on Vancouver Island?

    Most mortgage brokers help you get a mortgage. I help you think about your mortgage strategically, as a financial planning tool. I'm a Smith Manoeuvre Certified Professional, which means I can help you structure your mortgage to build wealth and reduce taxes simultaneously. That's not something you'll find at your bank, or with most brokers.

  • What’s the difference between using a bank and using a mortgage broker?

    Banks offer only their own mortgage products, and they often provide weak preapprovals. As a mortgage broker, I offer you access to multiple lenders, structures, and strategies, including readvanceable mortgages, refinancing options, debt-consolidation tools, and long-term planning support. And accurate preapprovals! My goal isn’t to sell a mortgage; it’s to be your debt advisor.

  • When should I consider refinancing my mortgage?

    Refinancing may make sense when you want to:


    • lower total borrowing costs
    • roll high-interest debt into lower mortgage rates 
    • access equity for investing or renovations
    • convert to a readvanceable structure

    I always calculate penalty costs versus benefits before moving forward.

  • What is a readvanceable mortgage?

    A readvanceable mortgage links a regular mortgage with a HELOC. As the mortgage balance decreases, available credit increases. This structure enables strategies like the Smith Manoeuvre and provides flexible access to home equity. Few homeowners make it through the entire amortization period without needing to access their equity to advance their goals.

  • Should I choose a fixed or variable rate?

    It depends on your:


    • risk tolerance
    • income stability
    • time horizon
    • likelihood of moving or refinancing
    • overall strategy (including tax planning)

    We review multiple scenarios so your rate decision aligns with your plan, not just today’s rate.


  • Is consolidating debt into my mortgage a good idea?

    It can be, if it reduces interest costs, improves cash flow, and prevents future debt buildup. The key is pairing consolidation with an intentional plan so the debt doesn’t reappear. We run numbers before making the decision.

  • Can my mortgage help me build wealth, not just pay debt?

    Yes, when structured intentionally. Using tools like readvanceable mortgages, disciplined investing, and tax-efficient strategies, your mortgage can become part of your wealth plan instead of just an expense. As a mortgage takes such a large part of your fiscal timeline, you can benefit from intentionally refinancing your loan over the repayment period. You can use your mortgage to both buy a home and build out your retirement needs.

  • How much down payment do I really need?

    In Canada:


    • 5% minimum on homes under $500,000
    • blended structure from $500,000 to $1,000,000, where it is 10% on the amount between $500,000 to $1,000,000.
    • 20% required on homes over $1,000,000, up to ~$1,500,000 depending on lender and location
    • Over $1,500,000 the down payment becomes 50% of the amount over.

    Your situation, credit, and goals determine the best approach, not just the minimum rules.


  • What costs should I expect when arranging a mortgage?

    Typical costs may include appraisal fees, legal fees, title insurance, transfer taxes, and possibly penalties if breaking an existing mortgage. We review everything upfront so there are no surprises, and I supply you with a full comprehensive breakdown of all your costs.

  • How often should my mortgage be reviewed?

    Ideally, once per year, and always at:


    • renewal time
    • major life changes
    • interest rate shifts
    • when tax or investment plans evolve

    Proactive reviews keep your mortgage aligned with your goals. You can use your Mortgage loan to achieve much more than just home ownership. Buying the home is the first step.

  • What’s the biggest mistake homeowners make?

    Treating the mortgage like a one-time transaction. The most successful homeowners think strategically, using their mortgage as a financial planning tool rather than just a loan to buy a house. The costs and timelines are too high and too long. My role is to help design and manage a long-term plan.


    I'm looking forward to hearing your thoughts on the above, and to making my web page the primary driver of new business for me.

  • How long does a mortgage pre-approval take?

    Typically 24 to 72 hours once I have your documents. I'll tell you exactly what to gather when we connect and I'll keep you informed at every step.

  • Can you help me if I have already started looking at homes?

    Absolutely. Reach out at any stage of the process. Whether you haven't started yet or you have an accepted offer on a property, I can help. The earlier the better, but it is never too late to get proper advice.

  • What is the Smith Manoeuvre and is it right for me?

    The Smith Manoeuvre is a Canadian financial strategy that converts your non-deductible mortgage interest into tax-deductible investment debt. Over time, it can help you pay off your mortgage 7 to 10 years faster while building an investment portfolio, without increasing your monthly payments. It works best for homeowners with a stable income who plan to stay in their home long-term. I offer a free personalized analysis to help you determine if it makes sense for your situation.

  • Do you serve all of Vancouver Island?

    Yes. I'm based in Courtenay, BC but I serve clients across Vancouver Island, including Comox Valley, Campbell River, Nanaimo, Parksville, Duncan, Port Alberni, and all of BC. Most of my work is done remotely, so geography is not a barrier.
Still have a question?

CONTACT ME